 Identity Card
 National Identity Document
 Citizenship ID
 Unique Identity Document
 Personal Identification Document
 Unique Population Registry Code
 Personal Identity Card
 Civil Identity Card
 Identity and Electoral Card
 Check Plate Colombia
 Check Plate Peru
 Check Plate Mexico
 Check Plate Argentina
 Check Plate Chile
 Check Plate USA
 Check Plate Brazil


Every fintech signup flow is a race between growth and fraud, and a modern eKYC for fintech platform has to win on both fronts: let real users in within minutes and keep fake identities out.
In the U.S., according to IdentityIQ data, alerts tied to potentially fraudulent new accounts rose 65% in 2025 versus 2024, driven by criminals using stolen and synthetic identities to open financial accounts. The same attack pattern reaches fintechs across Latin America.
In this guide you will see what eKYC means for a fintech, the KYC and AML requirements you must cover, the six-step verification process, how it looks in the API, the security-versus-completion trade-off, and why local LatAm coverage matters as much as the digital flow.
What eKYC means for a fintech
eKYC is the electronic version of Know Your Customer: verify who a user is, assess their risk and keep records that prove you did it. For a fintech, three parts of that work matter most.
Customer identification at signup
Before the first transaction, you must identify the person behind the account. In practice that means collecting a government-issued ID, extracting the data and matching a live selfie to the document photo. Regulators call this a Customer Identification Program, and it applies whether you are a bank, a lender or a wallet app.
Due diligence, not a one-time check
Verification does not end at signup. Customer due diligence means understanding who the customer is and watching for suspicious activity over the life of the account.
Fintechs that onboard businesses must also identify beneficial owners: every person with 25% or more ownership, plus one person with control. The U.S. FinCEN Customer Due Diligence Rule sets this standard, and in Colombia SARLAFT requires identifying the beneficial owner with the same logic.
Fintechs face bank-level rules
Regulators rarely give fintechs a softer version of the rules. A digital wallet or lending app is usually licensed as a financial institution or operates through a partner bank, and both paths carry the same AML expectations.
The FATF Recommendations, the international standard that most national AML rules follow, draw no distinction between a branch and an app.
Want to try it? Create your Verifik account and make your first call today.
The core KYC requirements for fintechs
Requirements differ by country, but the same four pillars show up almost everywhere. Fintech eKYC software must cover all of them in one workflow. For the broader frame, see also the eKYC compliance requirements.
1. Identity verification for every user
Collect and verify a government-issued ID for every individual user: national ID, passport or driver’s licence. The system must read the document, confirm it is genuine and match the applicant’s face to the photo. Names, ID numbers and dates of birth must be checked against the document itself, not only against what the user types.
2. Beneficial owners of business customers
If your fintech onboards businesses — for example merchants or SME borrowers — you must identify the real people behind them. That means every person with 25% or more ownership and one person with management control. Shell companies exist to hide ownership, so this check is where many fintechs fail their first regulatory assessment.
3. Sanctions and PEP screening
Every new user must be screened against sanctions lists, politically exposed person (PEP) databases and adverse media. Screening at onboarding alone is not enough: lists change daily, so your compliance policy must define when to re-check them by API. Missing a sanctioned person is one of the fastest ways to lose a licence. In practice that includes lists such as OFAC and the United Nations.
4. Ongoing monitoring
After onboarding, transactions must be monitored for suspicious patterns and customer information must stay up to date. A user who was low risk at signup can become high risk later. Regulators expect periodic reviews and a clear record of what was checked, when and why.
If you are building the programme from scratch, a KYC requirements checklist for fintech startups walks through each of these pillars in the order a new team should tackle them.
How the eKYC process works for fintech
A fintech signup flow typically runs six checks in sequence. A good KYC solution for fintech runs them in seconds and tells the user exactly what to do when something fails.
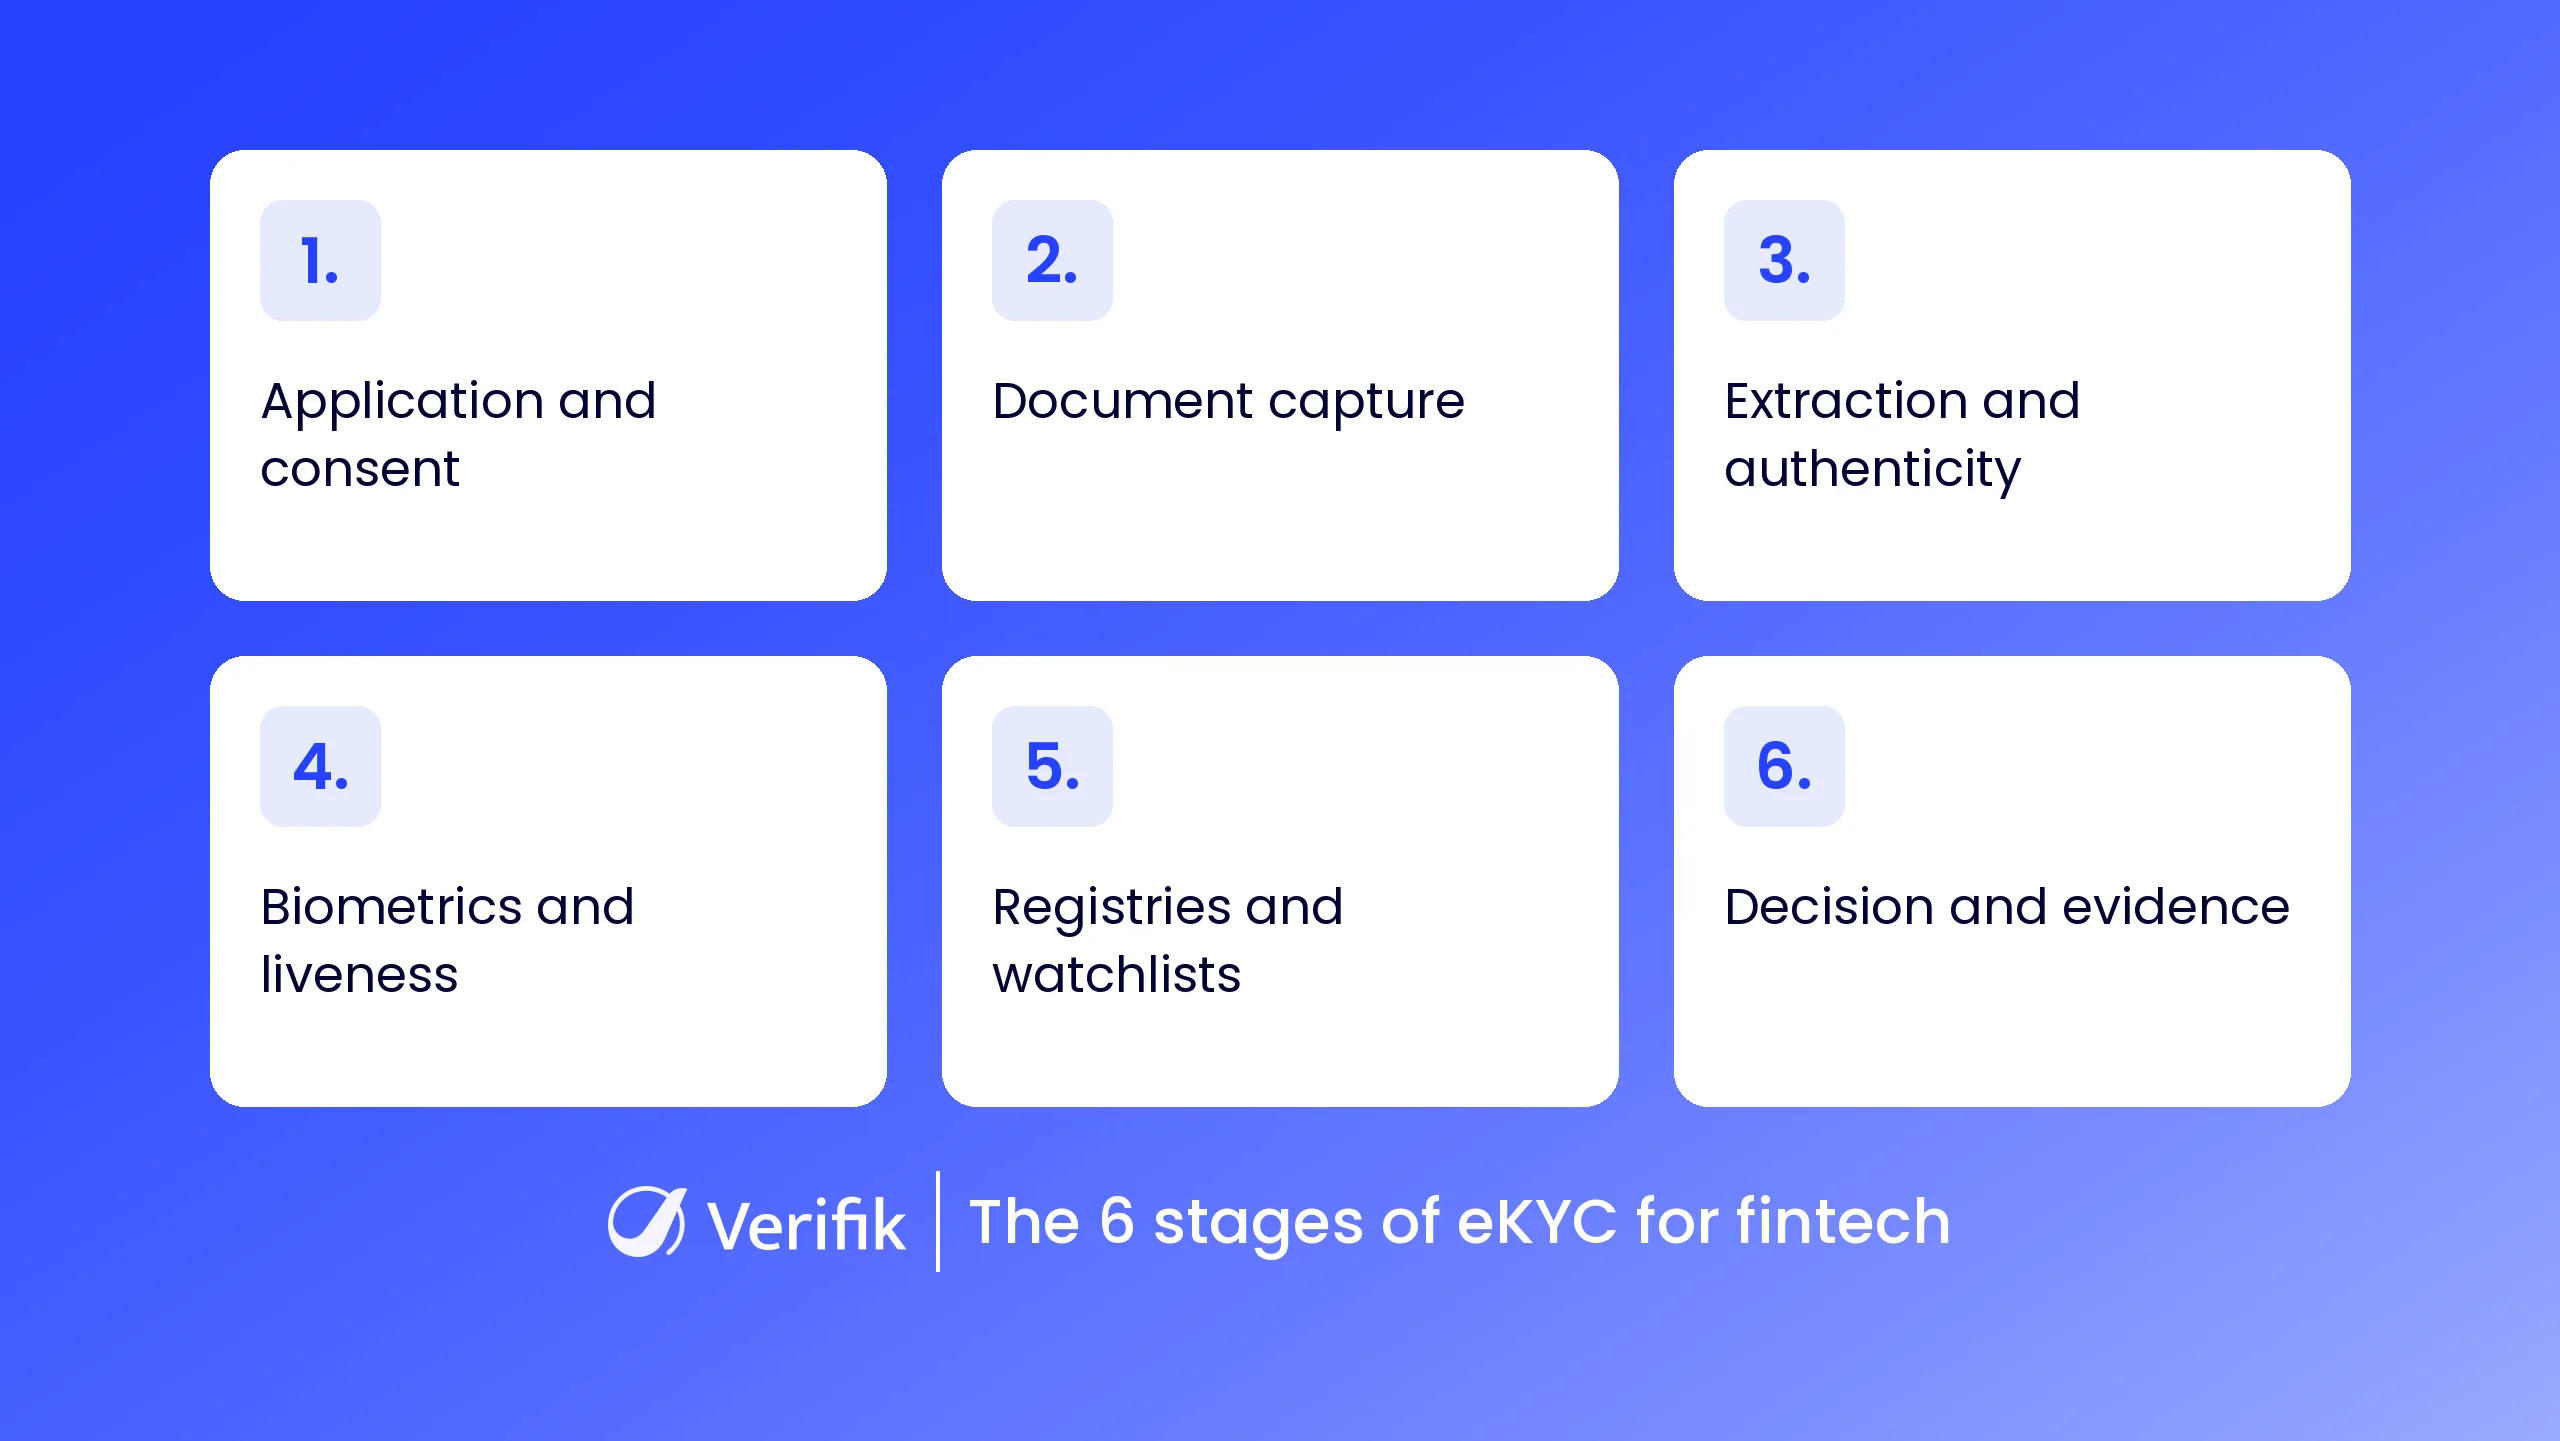
The journey feels continuous to the user; behind the scenes, every stage leaves evidence your compliance team can defend in an audit.
1. Application and consent
The user enters basic data and consents to identity checks. Consent wording matters: it must be clear, specific and stored, because data-protection rules in most markets require proof that the user agreed.
2. Document capture
The user photographs an ID with the phone camera. The best flows guide capture in real time and warn about blur, glare and cropped edges. Capture conditions are imperfect: low light, cracked screens, old cameras. Clear guidance here is the cheapest way to raise approval rates.
3. Data extraction and authenticity analysis
The system reads the document, extracts names and numbers into structured fields and checks the ID for forgery signals: swapped photos, wrong fonts and damaged security features. Catching a fake document at this point is far cheaper than catching fraud after the account is funded.
4. Biometric match and liveness detection
A live selfie is matched to the ID photo and liveness confirms a real person is in front of the camera. This blocks printed photos, replayed videos and masks. Single-image liveness (iBeta Level 2 certification) does not require head movements, so the experience stays smooth.
5. Registry and watchlist checks
Extracted identity data is checked against government registries, credit sources, sanctions lists and PEP databases.
In Latin America, the depth of local registries is what separates a real check from a superficial one: Colombia’s RUES business registry and SIMIT fines database, Brazil’s CNPJ, Argentina’s CUIT and the national ID systems behind the cédula, Mexico’s INE and Peru’s DNI. For the Colombian case, the Colombia KYC API hub summarises those sources.
6. The decision and the evidence record
All signals combine into a single decision with a full evidence record: what was checked, what passed, what failed and when. Clear cases are approved automatically. Uncertain cases go to a human reviewer with everything already gathered on one screen.
To see the full step-by-step flow focused on a fintech signup, see How eKYC for fintech works: from signup to verified user.
How it looks in the API
These are the calls that typically make up a fintech onboarding with Verifik. Use process.env.VERIFIK_TOKEN (or $VERIFIK_TOKEN in cURL); never paste a real token into your code.
Face match with liveness
POST /v2/face-recognition/compare-with-liveness matches the selfie to the document face and, if the compare threshold is met, runs liveness on the probe.
curl -X POST "https://api.verifik.co/v2/face-recognition/compare-with-liveness" \
  -H "Content-Type: application/json" \
  -H "Authorization: Bearer $VERIFIK_TOKEN" \
  -d '{
    "probe": "<selfie_base64>",
    "gallery": ["<document_face_base64>"],
    "search_mode": "FAST",
    "liveness_min_score": 0.6,
    "compare_min_score": 0.8
  }
import axios from "axios";
const { data } = await axios.post(
"https://api.verifik.co/v2/face-recognition/compare-with-liveness",
{
probe: process.env.PROBE_B64,
gallery: [process.env.GALLERY_B64],
search_mode: "FAST",
liveness_min_score: 0.6,
compare_min_score: 0.8,
},
{
headers: {
"Content-Type": "application/json",
Authorization: `Bearer ${process.env.VERIFIK_TOKEN}`,
},
}
);
console.log(data);{
"id": "CWL01",
"comparison": {
"score": 0.88,
"passed": true,
"compare_min_score": 0.8
},
"liveness": {
"liveness_score": 0.91,
"min_score": 0.6,
"passed": true
},
"signature": {
"message": "Certified by Verifik.co",
"dateTime": "January 16, 2024 3:44 PM"
}
}Validate the extracted ID
GET /v2/co/cedula confirms the name and document status against Colombia’s Registraduría (CC or PPT).
curl -G "https://api.verifik.co/v2/co/cedula" \
  -H "Accept: application/json" \
  -H "Authorization: Bearer $VERIFIK_TOKEN" \
  --data-urlencode "documentType=CC" \
  --data-urlencode "documentNumber=123456789"
{
"data": {
"documentType": "CC",
"documentNumber": "1121329662",
"firstName": "JULIO CESAR",
"lastName": "CABANA CONTRERAS",
"fullName": "JULIO CESAR CABANA CONTRERAS"
},
"signature": {
"message": "Certified by Verifik.co",
"dateTime": "October 8, 2025 8:21 PM"
},
"id": "I70IL"
}Business onboarding (KYB) with RUES
GET /v3/co/rues-complete returns the full commercial dossier for a NIT (RM category by default).
curl -G "https://api.verifik.co/v3/co/rues-complete" \
  -H "Accept: application/json" \
  -H "Authorization: Bearer $VERIFIK_TOKEN" \
  --data-urlencode "category=RM" \
  --data-urlencode "documentType=NIT" \
  --data-urlencode "documentNumber=900123456"
{
"data": {
"commercialRegistry": {
"NIT": "900123456",
"businessName": "FINTECH EJEMPLO S.A.S.",
"chamberCommerce": "BOGOTA",
"registrationStatus": "ACTIVA",
"companyType": "SOCIEDAD POR ACCIONES SIMPLIFICADA"
}
},
"signature": {
"message": "Certified by Verifik.co",
"dateTime": "October 6, 2025 3:11 PM"
},
"id": "2VTPR"
}Read the smartENROLL result in your backend
GET /v2/app-registrations/:id?populates[]=compareFaceVerification exposes result.score, result.passed and result.compare_min_score. If the ProjectFlow has a webhook, the typical final event is onboarding_app_registration_completed.
curl -G "https://api.verifik.co/v2/app-registrations/APP_REGISTRATION_ID" \
  -H "Accept: application/json" \
  -H "Authorization: Bearer $VERIFIK_TOKEN" \
  --data-urlencode "populates[]=compareFaceVerification"
{
"data": {
"status": "COMPLETED",
"compareFaceVerification": {
"result": {
"score": 0.91,
"passed": true,
"compare_min_score": 0.85
},
"comparedAt": "2026-10-15T18:22:01.000Z"
}
},
"signature": {
"message": "Certified by Verifik.co"
}
}Traditional KYC vs eKYC
The contrast between traditional KYC and eKYC is clearest side by side.
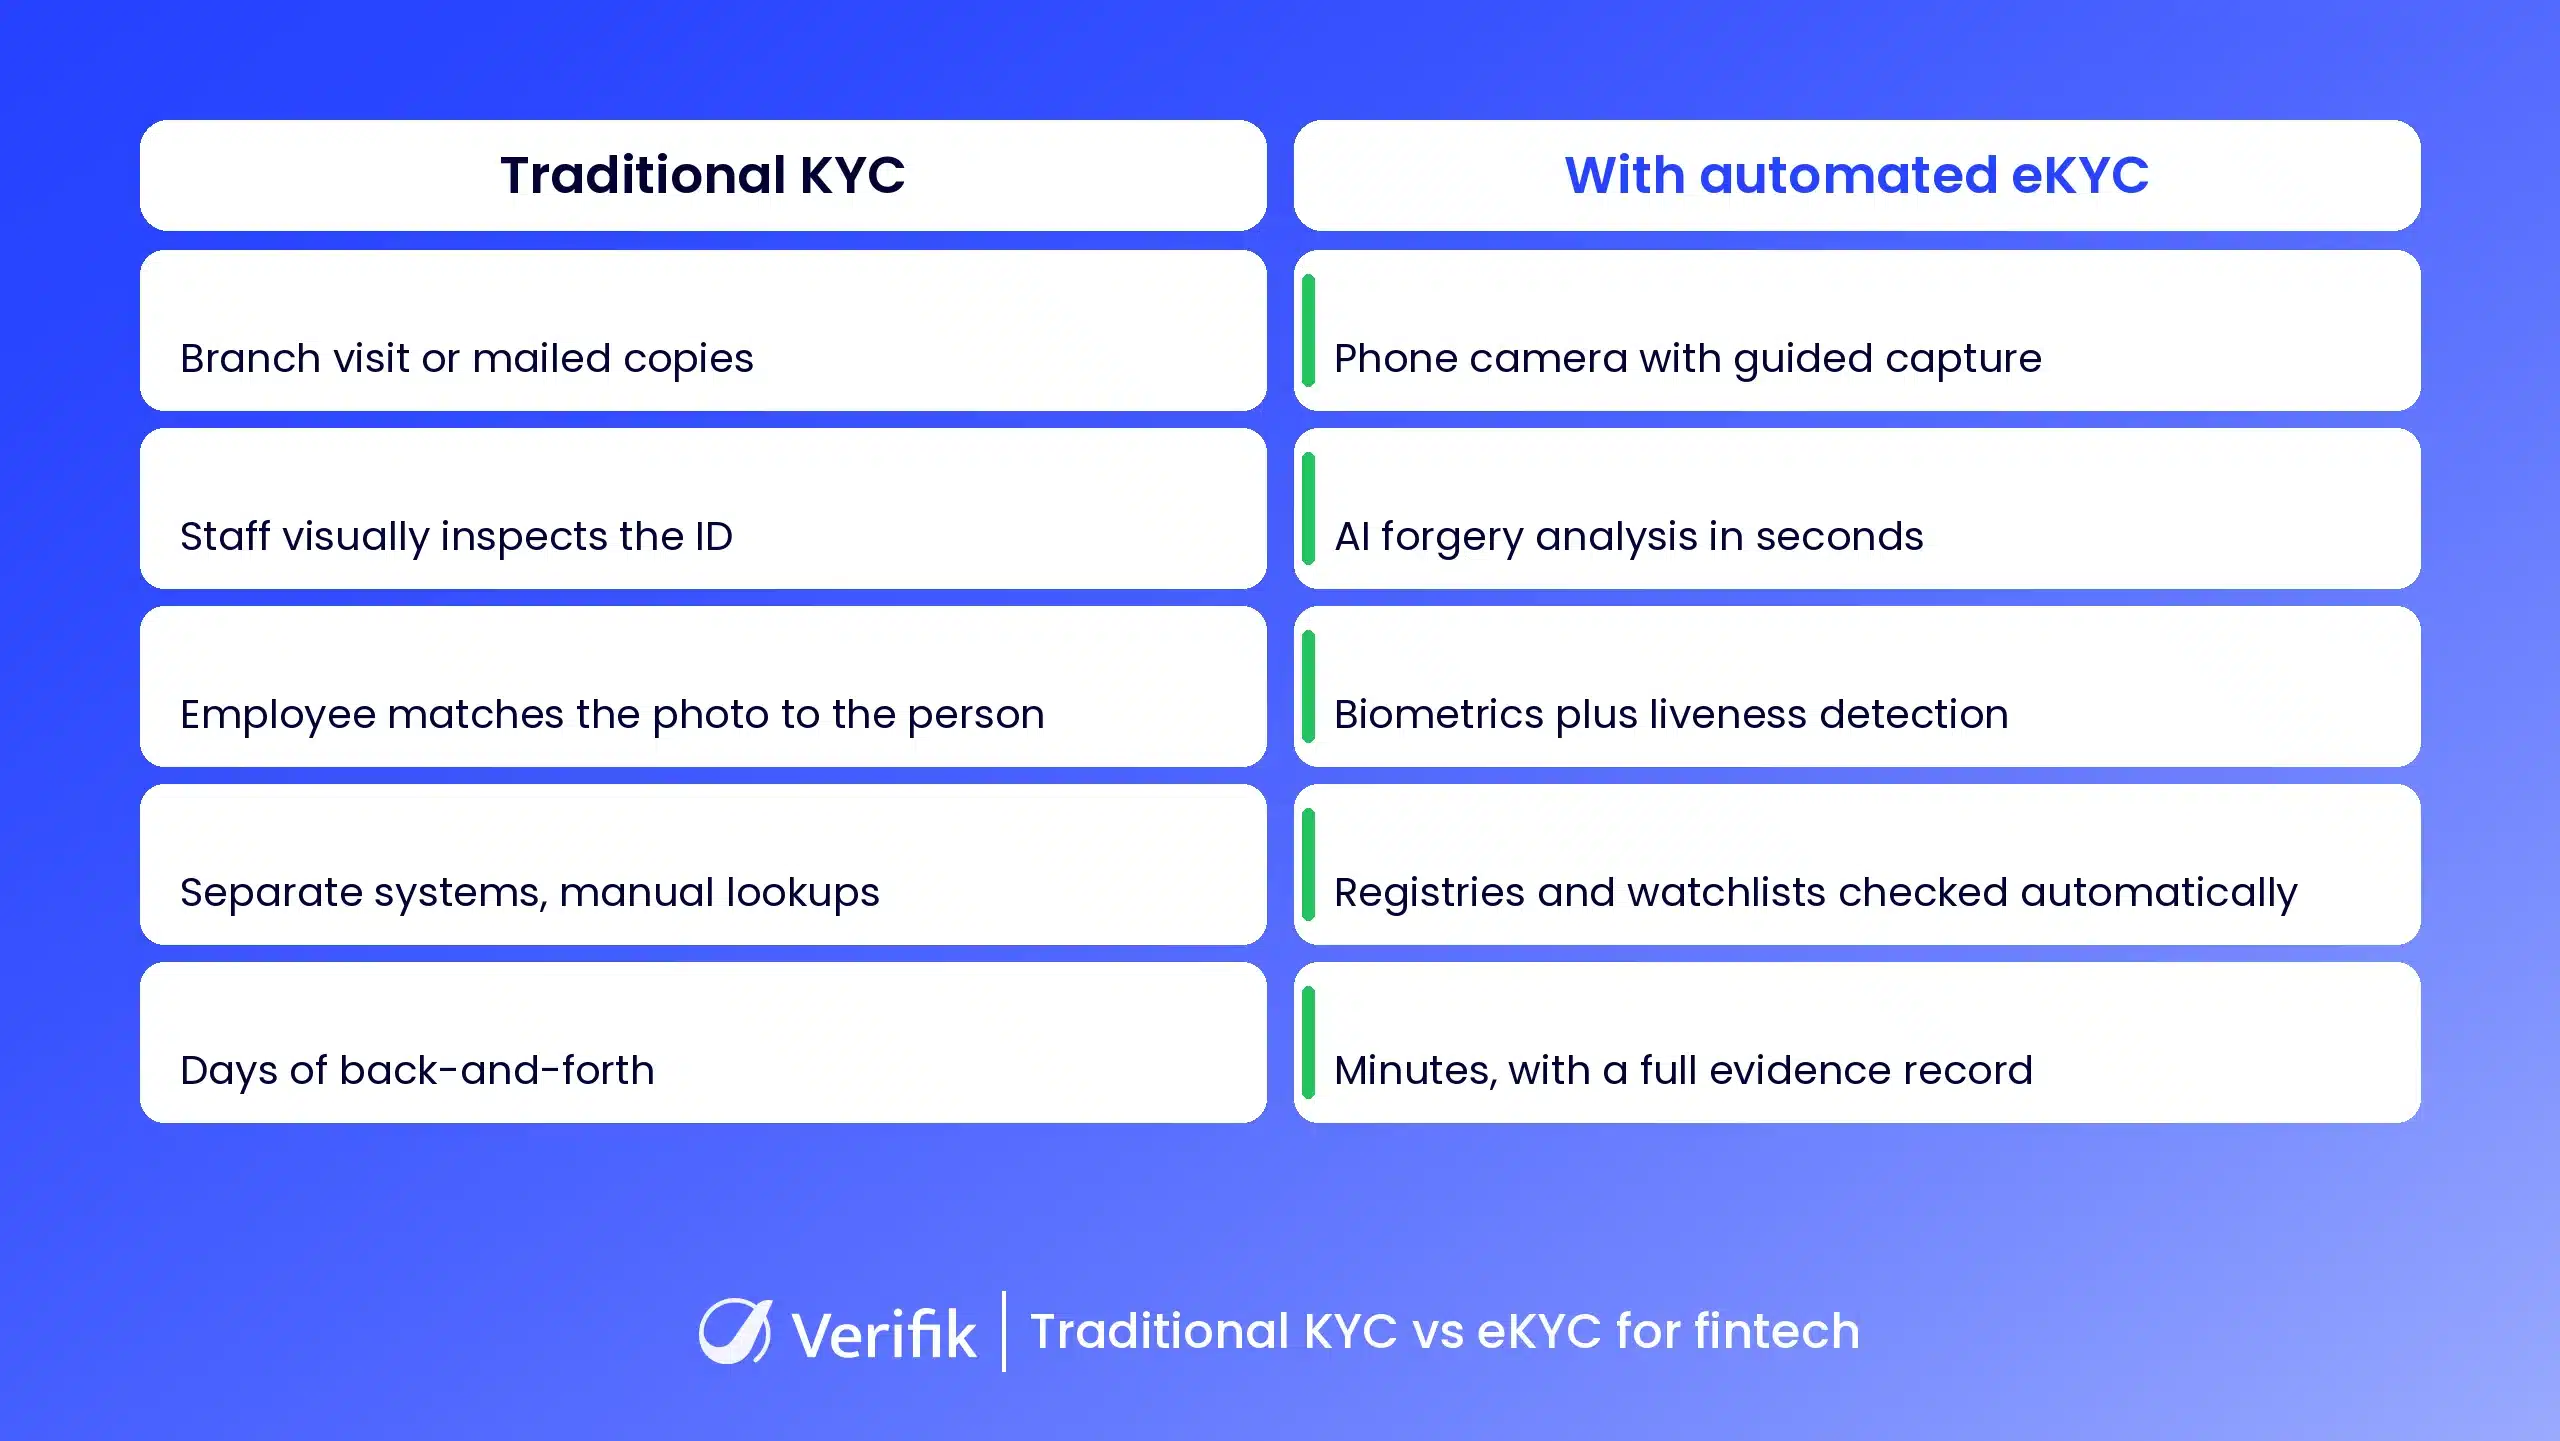
The table summarises the operational difference: the digital channel, time to decision and where the evidence of each check lives.
| Traditional KYC | With automated eKYC |
|---|---|
| Branch visit or mailed copies | Phone camera with guided capture |
| Staff visually inspects the ID | AI forgery analysis in seconds |
| Employee matches the photo to the person | Biometric match plus liveness |
| Separate systems, manual lookups | Registries and watchlists checked automatically |
| Days of back-and-forth | Minutes, with a full evidence record |
The benefits fintechs actually get
Higher signup completion
Most applicants who start a digital application never finish it. Abandonment rises sharply when an application takes more than a few minutes. Every minute and every confusing screen you remove turns directly into funded accounts.
Lower fraud losses
Fraud losses cost far more than the amount stolen: investigation, fines and remediation multiply every dollar lost. Stopping fake identities at signup is the cheapest anti-fraud control a fintech has.
Lower cost per verification
Manual identity review is expensive and does not scale. Automated checks cost a fraction of a manual review, and the gap only widens with volume. For a fintech onboarding thousands of users a day, that cost difference decides whether growth is profitable.
Faster time to market
A fintech that builds manual review teams before launch moves slowly and hires staff before it earns revenue. An automated eKYC flow lets a small team launch in weeks, handle volume spikes without new hires and enter the market while competitors are still staffing operations.
The core trade-off: security vs. completion
Every check you add improves security and loses more applicants. That is the central eKYC design trade-off, and there is no version where both numbers move in the same direction.
A five-step flow with document checks, biometrics, liveness, registries and watchlists will catch more fraud than a two-step flow, and will also convert fewer real users.
Friction does not only slow fraudsters. It sends good customers to whoever asks for less. Industry research consistently finds that a sizeable share of applicants will abandon a flow that forces them out of the digital channel.
The real answer is risk-based design: order checks by cost, run the cheapest ones first and reserve the harder checks for the cases that need them.
A low-risk domestic user might pass with document and liveness alone, while a high-risk profile triggers deeper registry validation and manual review. Conditions differ by country and product, so confirm your risk tiers with your own compliance team and supervisor instead of copying another market’s setup.
The Latin America layer
Fintechs expanding across Latin America face a verification problem that global vendors underestimate. Digital onboarding for fintech apps in this region must handle many document formats, many registries and many regulators at once.
National IDs differ by country
Colombia’s cédula, Mexico’s INE card and Peru’s DNI look nothing alike, and each has its own security features and data formats. A document model trained only on U.S. driver’s licences will misread them. Test local ID coverage first in any vendor demo.
Local registries are the real verification
Watchlists are global, but the truth about identity lives in local registries: Colombia’s RUES business registry and SIMIT fines database, Brazil’s CNPJ business registry and Argentina’s CUIT tax ID system.
A check that never queries these sources is comparing the ID to itself. Verifik’s advantage is depth here: dozens of Latin American data endpoints that global tools simply do not query.
Regulators expect local coverage
Colombia’s Financial Superintendence, Mexico’s CNBV and Peru’s SBS each set their own remote-identification rules.
In Colombia, External Circular 027 of 2020 (SARLAFT 4.0) from the Financial Superintendence allows digital onboarding with biometrics, digital signature and reliable independent sources, removes the mandatory vinculación form and adds simplified onboarding for low-value products. Law 2573 of 2026 requires financial and credit entities to take sufficient and reasonable measures to verify the person and the document; it takes effect on 19 November 2026 and the SIC protocol is still pending.
The region’s fintech sector has grown quickly in recent years, and supervisors are tightening expectations as it matures. Confirm the details of each market with local legal counsel.
If you are expanding beyond one market, KYC for fintech at scale: verifying users in new markets explains how to verify users when you enter new countries.
What regulators expect behind the scenes
Regulators do not prescribe a specific technology. The FATF Guidance on Digital Identity states that its standards are technology-neutral and allow remote identity verification, so eKYC is treated as equivalent to in-person verification in most markets. You can read the guidance on the FATF website.
What examiners do demand is evidence: timestamped records of every check, the evidence behind every decision and ongoing monitoring after onboarding. Keep the records for years, because assessments look backwards.
A real limitation: no vendor can promise compliance in every country. Rules on data storage, biometric consent and which documents are accepted differ from market to market. Treat any eKYC vendor as a tool inside your compliance programme, not a replacement for it.
Why fintechs choose smartENROLL for eKYC
smartENROLL is Verifik’s eKYC solution built for fintechs in Latin America, where ID-format variety, strict regulators and uneven registry access make generic global tools struggle. The banking sister guide is eKYC for banks.
Document verification tuned for the region
It reads and verifies national IDs, passports and driver’s licences from Latin America with high accuracy, including Colombia’s cédula and formats that global vendors often misread.
Biometrics with single-image liveness
It matches the applicant’s face to the ID photo and confirms a real person is present, with single-image liveness certified iBeta Level 2, blocking photo, video and mask attacks without awkward head-movement exercises.
Deep registry validation
It checks applicants against local registries such as RUES and SIMIT, plus international sources, through dozens of Latin American data endpoints. Local coverage is what separates a real check from a box-ticking exercise.
Built-in watchlist screening
Sanctions, PEP and adverse-media screening runs during onboarding. When your policy requires it, you re-check the same lists by API (OFAC, UN, EU, UK OFSI and others) without maintaining spreadsheets by hand.
Risk tiers your team controls
From project settings you choose countries, documents, flow steps and thresholds (for example compare_min_score between 0.67 and 0.95, with 0.85 as the hosted default; liveness_min_score default 0.6), so the security-versus-completion trade-off stays in your hands.
API-first, built for fintech stacks
smartENROLL offers a hosted no-code flow, a self-hosted API version (SmartEnroll v3), lifecycle webhooks and a development environment, so your developers can integrate and iterate without vendor tickets.
Ready to try it on your own signup flow? Book a demo and watch a live verification from document capture to decision.
Design your fintech eKYC with evidence, not promises
eKYC for fintech comes down to four requirements, a six-step process and clear benefits: higher completion, lower fraud losses, lower cost per verification and faster launches. The fintechs that win treat verification as both a product and a compliance problem, and deliberately design the security-versus-completion trade-off, market by market.
The fastest way to evaluate any platform is to put your own applicants through it and watch where they struggle. smartENROLL is built exactly for that test, with Latin American document and registry coverage that global tools cannot match.